
Five-Year Stock Market Forecast: Will the Bull Market Last Through 2032?
U.S. economic outlook, S&P 500 and Nasdaq projections, political risks and 30 long-term stocks to watch | Updated November 12, 2026
What might your investments be worth five years from now? It is a more valuable question than guessing tomorrow’s closing price. Between 2027 and early 2032, American businesses will confront another election cycle, shifts in interest rates, changing trade policy and perhaps the greatest industrial investment boom since the internet age.
The opportunity in this potential continuous bull market is substantial. US leadership in AI and robotics might also be big reasons to reader this report further. Yet, so is the danger of paying too much for stocks. A successful five-year forecast isn’t so much a prophecy, however, self-managed investors usually want the clarity of a stock market prediction. Predicting the stock market tomorrow or next week or next 3 months is difficult enough, but 5 year projections are a massive proposition.
Why The 5 Year Outlook is a Powerful Investment Horizon
Five years gives factories time to open, AI systems time to produce measurable productivity gains and US businesses time to turn spending into earnings. It also provides enough time for a recession, market correction or political reversal. 2032 could look very different for many reasons.
Leading Forecaster’s Expectations
| Forecaster | Published long-range outlook | Interpretation |
|---|---|---|
| Vanguard, October 2026 | 4.8%–6.8% annually for U.S. equities over 10 years | Positive, but below the recent extraordinary bull-market experience. |
| J.P. Morgan Asset Management, October 2026 | 7.5% annually for U.S. large caps over 10–15 years | AI productivity and corporate margins support returns; valuations remain a concern. |
| State Street, Q4 2026 | 6.9% annually for U.S. large caps over 3–5 years; 7.4% for small caps | Broader participation is plausible, not assured. |
| Ed Yardeni, September 2026 | S&P 500 at 10,000 by 2030 | An optimistic end-of-decade target, though Yardeni raised near-term bearish odds. |
These forecasts differ in horizon, methodology and treatment of dividends. They are not interchangeable predictions of the S&P 500’s price on January 1, 2032.
U.S. Economic Growth: What Will Drive Stock Prices
The Federal Reserve’s September projections anticipate 2.4% real GDP growth in 2027, 2.2% in 2028 and 2.1% in 2029, measured fourth-quarter to fourth-quarter. The more conservative Congressional Budget Office February baseline projects 1.9% growth in 2027 and 1.8% annually in 2028–2032, using annual-average growth. The different measures and publication dates help explain the gap.

The economic expansion may become less dependent on consumer spending and more on investment in data centers, electricity, advanced manufacturing, defense and infrastructure. The Conference Board’s October forecast expects 2.1% GDP growth in 2027 but warns that an extended energy shock could jeopardize expansion.
Key Factors: Jobs, Wages, Inflation and Interest Rates
October 2026 payrolls rose 165,000, unemployment was 4.1% and average hourly earnings increased 3.1% year over year, according to the Bureau of Labor Statistics. A healthy wage gain supports spending, although weak hiring or wages rising slower than prices would pressure budgets. CBO forecasts private-industry wage growth of 3.2% in 2027 and about 3.0% annually in 2028–2036.
The Fed’s September median projections keep unemployment near 4.1% through 2029, anticipate PCE inflation declining from 3.7% in 2026 to 2.3% in 2027 and 2.0% by 2029, and show the policy rate around 4.1% in 2027, easing to 3.6% in 2029. These are policymakers’ conditional estimates, not promised rate cuts. High government borrowing and a new inflation shock could keep rates elevated.
Earnings growth: Where the Bull Market Case becomes Measurable
Stocks ultimately depend on cash flows and earnings. FactSet’s November 6 Earnings Insight shows bottom-up S&P 500 earnings-per-share estimates of $365.35 for 2026 and $424.96 for 2027—about 16.3% expected growth. These estimates will change as companies report results. An index can rise with earnings even if investors become unwilling to pay higher earnings multiples.
That distinction matters when debating a bubble. Real AI revenues and corporate profits can soar while certain speculative valuations collapse. Watch free cash flow, profit margins, return on invested capital and whether growth extends beyond a few enormous technology companies.
AI, Robotics and the Investment Supercycle
Goldman Sachs Research estimates $581 billion of AI-related investment in the United States during 2026, within roughly $1 trillion globally. This spending creates orders for chips, electrical systems, cooling, power generation, construction and communications equipment.
The next phase is more important: can businesses use AI and robotics to produce more with fewer wasted hours, improve logistics, create new services and expand profit margins? The strongest long-term winners may include electricity and industrial automation suppliers, cybersecurity providers and successful AI adopters—not merely companies promoting an AI narrative. Heavy capital expenditure, financing costs and technology obsolescence remain threats.
Oil, the dollar and America’s manufacturing advantage
Energy is both an opportunity and a tax on growth. The EIA’s November 2026 outlook forecasts Brent oil averaging $97 a barrel in 2026 and $86 in 2027. High prices lift oil-producer cash flow but squeeze airlines, trucking, chemicals, manufacturing and consumers. An enduring Middle East disruption would change the picture sharply.
A stronger dollar can lower the dollar cost of imported materials and machinery, helping U.S. companies that buy abroad, while hurting exporters’ price competitiveness and the translated foreign profits of multinationals. A weaker dollar often reverses those effects. Tariffs may offset import-cost savings, even as they encourage domestic sourcing. The winning company is one with pricing power, resilient suppliers and productive U.S. operations—not simply one labeled “made in America.”
Policy and politics will shape the winners
The 2025 tax law extended major Trump-era individual provisions and restored immediate deductions for many equipment and domestic research investments; its incentives can support capital spending. But reduced revenue adds pressure to federal deficits, potentially increasing bond yields. CBO estimates a $1.9 trillion federal deficit in 2026, rising to $3.1 trillion by 2036.
Tariffs can protect selected domestic industries and encourage reshoring, but also raise input costs for American manufacturers. Restrictive immigration can reduce labor supply and increase wage pressure; automation may mitigate only part of that effect. Wars and defense policy affect military contractors, shipping, energy and inflation.
The November 2026 midterms have also changed the outlook: Democrats won control of both chambers of Congress, creating greater scope for oversight and legislative confrontation with the Trump administration. Future Democratic proposals for higher corporate or capital-gains taxes, stronger regulation and clean-energy support would influence after-tax returns.
How do we Quantify the Threat of an Economic Downturn?
Both political outcomes can occur during the same five-year window. The constructive case combines rising earnings, AI-driven productivity, stable employment, manageable inflation and a broadening rally. The bearish case involves stalled AI spending, expensive financing, geopolitical shocks, tariffs, shrinking profit margins or a recession. The AI industry isn’t likely poised for a collapse, but reducing the commitment to something so important to the US economy is a risk. There is more at stake than a collapse of AI stock prices.
Valuation discipline remains essential. Speculative stocks without dependable cash flow face the greatest risk if optimism fades. Strong profitable companies can also suffer sharp corrections. An investor should prepare for volatility rather than assume five straight years of gains.
Which sectors could outperform—and which might struggle?
Promising: electricity generation and grid equipment, cybersecurity, industrial robotics, automation, defense, advanced chips and profitable healthcare innovation. Quality financials could benefit from sustained lending and investment, while selected energy producers may serve as a hedge against oil shocks.
More vulnerable: highly indebted firms, unprofitable technology businesses, rate-sensitive real estate, discretionary retailers with weak pricing power and import-dependent manufacturers unable to pass through tariffs. Even favored sectors can disappoint if valuations already price in exceptional growth.
Cash on the Sidelines: Fuel for Another Rally?
The Investment Company Institute reported $8.02 trillion in money-market fund assets on November 4, 2026. Some money may move toward stocks if yields fall, but it is misleading to regard the entire sum as waiting to enter equities. Much finances routine liquidity needs and institutional cash management; selling a money-market fund to buy a stock simply transfers cash to another holder.
S&P 500, Dow, Nasdaq and Russell 2000: Scenarios to 2032
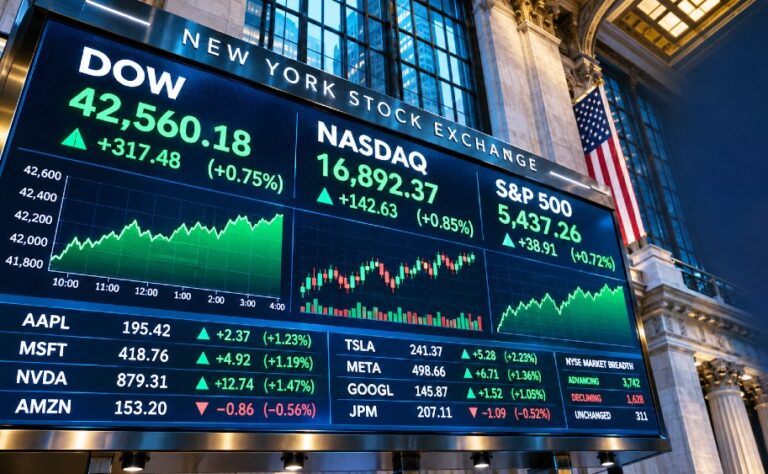
Using November 11, 2026 closing levels as starting points, let’s project these index predictions over approximately five years.
| Index | Nov. 11, 2026 | Bear case | Base case | Bull case |
|---|---|---|---|---|
| S&P 500 | 7,619 | 6,543 | 10,196 | 12,271 |
| Dow Jones | 52,486 | 47,444 | 66,988 | 80,757 |
| Nasdaq Composite | 25,466 | 19,705 | 35,718 | 46,920 |
| Russell 2000 | 2,846 | 2,321 | 3,809 | 5,016 |

Annual assumptions, respectively bear/base/bull: S&P −3%/+6%/+10%; Dow −2%/+5%/+9%; Nasdaq −5%/+7%/+13%; Russell −4%/+6%/+12%. Nasdaq results are especially sensitive to technology valuations; small caps depend heavily on credit availability and domestic demand. The Dow offers more mature-business exposure, while the S&P blends mega-cap innovators with the wider U.S. economy.
Thirty stocks with potential through 2032
These are research candidates, not buy recommendations or an equal-weight model portfolio. Several carry high valuations, cyclical exposure or regulatory risks. Verify debt, free cash flow and purchase price before investing.
| Company (ticker) | Five-year opportunity | Principal risk |
|---|---|---|
| Nvidia (NVDA) | AI accelerators and software ecosystem | Competition; AI spending slowdown |
| Broadcom (AVGO) | Custom AI chips and networking | Customer concentration |
| AMD (AMD) | AI chips and server processors | Rival technology and margins |
| Micron (MU) | High-bandwidth memory | Memory price cycles |
| Applied Materials (AMAT) | Semiconductor equipment demand | Export restrictions |
| Microsoft (MSFT) | Enterprise AI and cloud services | Monetization versus AI capex |
| Alphabet (GOOGL) | Search, cloud and AI distribution | Antitrust; search disruption |
| Amazon (AMZN) | AWS, logistics automation | Capital spending and retail margins |
| Meta Platforms (META) | Advertising and AI recommendations | Regulation; platform spending |
| Oracle (ORCL) | Cloud infrastructure contracts | Debt and execution |
| ServiceNow (NOW) | Workflow AI adoption | Software valuation |
| Palo Alto Networks (PANW) | Consolidated cyber defenses | Intense competition |
| CrowdStrike (CRWD) | Endpoint and cloud security | Execution; valuation |
| Vertiv (VRT) | Data-center power and cooling | Construction cycle |
| Eaton (ETN) | Electrical equipment and grid upgrades | Premium valuation |
| Quanta Services (PWR) | Transmission and infrastructure buildout | Project execution |
| GE Vernova (GEV) | Grid equipment and turbines | Project and supply-chain risks |
| Constellation Energy (CEG) | Nuclear electricity demand | Energy regulation and pricing |
| NextEra Energy (NEE) | Utility and electricity investment | Interest rates and capital needs |
| Caterpillar (CAT) | Power and industrial equipment | Global economic cycles |
| Deere (DE) | Precision agriculture and autonomy | Farm income weakness |
| Rockwell Automation (ROK) | Factory automation | Industrial spending cycles |
| Lockheed Martin (LMT) | Advanced defense programs | Procurement and budget risk |
| RTX (RTX) | Defense systems and aerospace | Contract and supply-chain costs |
| Intuitive Surgical (ISRG) | Robotic-assisted surgery | Competition; hospital budgets |
| Eli Lilly (LLY) | Metabolic-health treatments | Pricing and competition |
| JPMorgan Chase (JPM) | Lending and financial scale | Credit losses; regulation |
| Visa (V) | Digital payments expansion | Payment-fee regulation |
| Exxon Mobil (XOM) | Energy supply and cash returns | Oil-price decline |
| Chevron (CVX) | Energy production and dividends | Commodity and project risk |
Have $2,000 to $10,000 of Gambling Cash?
A lot of retail investors have an amount of cash they can invest in more speculative stocks. The upside, especially within a rosy economic outlook is pronounced. You could invest your rrsp or 401k in safe stocks and use your other cash for companies that might really go big. After all, some of those tech stocks went 4x to 10x over the last 5 years. That kind of return is very inviting, and for some life changing. Investing in high potential, speculative small caps isn’t such a bad investment choice.
But you need to know why you’re buying those stocks. The best stocks to buy have strong fundamentals too. Here’s a few to consider:
30 speculative small/mid-cap stocks with High Upside Potential
| Company / ticker | What could drive substantial gains? | Principal risk |
|---|---|---|
| AI chips and software | ||
| Arteris (AIP) | AI chiplet and interconnect technology | Licensing volatility |
| Cohu (COHU) | AI semiconductor testing demand | Chip investment cycles |
| Everspin (MRAM) | Next-generation persistent memory | Small scale, competition |
| Innodata (INOD) | AI data engineering and evaluation | Customer concentration |
| Alpha & Omega (AOSL) | AI-server power components | Weak margins |
| Robotics and automation | ||
| Ouster (OUST) | Sensors and perception for robotics | Losses, dilution |
| Allient (ALNT) | Precision motors and robotic actuators | Industrial cycles |
| Serve Robotics (SERV) | Autonomous delivery robots | Unproven profitability |
| Palladyne AI (PDYN) | Autonomous defense technology | Early-stage commercialization |
| Proto Labs (PRLB) | Rapid manufacturing for robotics | Competitive margins |
| Space and satellites | ||
| Intuitive Machines (LUNR) | Lunar infrastructure and defense systems | Mission failures |
| Planet Labs (PL) | Satellite imagery and AI analytics | Capital costs |
| BlackSky (BKSY) | Defense intelligence from satellites | Dilution, launch risks |
| Redwire (RDW) | Space infrastructure and drones | Cash burn, integration |
| Voyager Technologies (VOYG) | Space stations and lunar services | Funding, contract delays |
| Defense technology | ||
| Kratos (KTOS) | Autonomous military aircraft | Program delays |
| Karman (KRMN) | Missile and propulsion components | Valuation, debt |
| Red Cat (RCAT) | Military drone production | Scaling difficulties |
| Ondas (ONDS) | Autonomous drones and counter-drone systems | Acquisition execution |
| AeroVironment (AVAV) | Tactical drones and defense systems | Procurement risk |
| Energy and strategic materials | ||
| Eos Energy (EOSE) | Long-duration battery storage | Manufacturing execution |
| Energy Fuels (UUUU) | Uranium and rare-earth processing | Commodity cycles |
| Centrus Energy (LEU) | Domestic nuclear fuel enrichment | Policy, contract timing |
| ASP Isotopes (ASPI) | Advanced isotope separation | Technical and regulatory risk |
| Ur-Energy (URG) | Uranium production expansion | Debt, uranium prices |
| Frontier technology and biotechnology | ||
| Enovix (ENVX) | Advanced batteries for drones and devices | Production scale-up |
| Beam Therapeutics (BEAM) | Precision gene editing | Clinical trial outcomes |
| Recursion (RXRX) | AI-assisted drug discovery | Clinical setbacks |
| Quantum Computing Inc. (QUBT) | Photonics and quantum applications | Unproven commercial scale |
| CRISPR Therapeutics (CRSP) | Gene-editing treatments | Adoption, clinical risk |
Note: Risk levels range from high to extreme. Companies with losses, financing needs, clinical trials or unproven technologies could suffer 50%–100% capital losses. The upside drivers shown above are hypotheses, not projected stock-price gains.
How to Approach the Next 5 Years
The smartest question is not “Which stock will triple?” but “Which businesses can still grow earnings if interest rates, energy costs and government priorities change?” Risk off investors can compare stock valuations with realistic profit growth; avoid concentration in one technology theme; maintain liquidity for near-term needs; and revisit the thesis rather than reacting to every market dip.
The bull market could survive well into the 2030s. It could also suffer a painful reset before recovering. Don’t view the rallies or the corrections but take a broader long term view of the value of these companies and their ability to produce earnings. The past might tell you a lot. More dips will likely happen. Your 5-year perspective gives you the discipline to distinguish a temporary decline in share prices from a lasting impairment of business value—and to seek opportunity without confusing optimism with certainty.
See more on the stock market today with views forward to next week and into three months ahead. Get a comprehensive view of the current US stock market to split your investments between safer blue chips above with some higher risk speculative stocks that could give you the big returns you really want.
Research note: Information is current to November 12, 2026. Economic and market projections can change. This article is educational commentary, not personalized investment advice.