Stock Market Forecast for the Next 3 Months
Updated November 3, 2026. Forecast window for this post: November 4, 2026–February 3, 2027
Will the stock market rise over the next three months—or are investors about to discover that the recent correction was only the beginning?
The answer may depend less on whether America’s biggest companies can grow and more on what investors are willing to pay for that growth. After months of volatility, persistent energy-price shocks, the AI-stock selloff and an increasingly restrictive bond market, the stage is set for either a selective rebound or another difficult repricing of stocks.
Our three-month U.S. stock market outlook is cautiously bullish, but not broadly bullish. Corporate earnings remain a substantial support. The danger is that higher interest rates, another Middle East energy shock, or disappointing cash returns from AI spending could overwhelm even good company results.
For investors, this could be a rewarding period to build positions in quality companies—but a poor time to buy every falling stock indiscriminately.
The S&P 500 closed November 3 at 7,568.92, with the Nasdaq Composite at 25,372.01 and the Dow at 51,786.72. Those closing levels are the fixed benchmarks for this forecast. The U.S. midterm elections are being held today, so their impact is not yet been seen. See more on the the forecast for the week ahead and a few expert stock market predictions.
The 3-Month Stock Market Forecast at a Glance
| Forecast question | Our November 2026 assessment |
|---|---|
| Most likely market path | Volatile consolidation followed by a selective recovery, assuming earnings and energy conditions stabilize. |
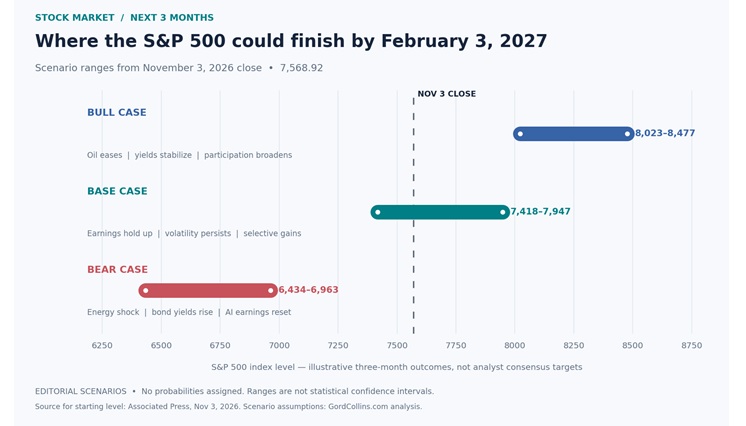
| S&P 500 base-case range, February 3, 2027 | 7,400–8,000, or −2% to +5% from November 3. |
| Where opportunities may emerge | Profitable AI infrastructure, industrial electrification, durable cloud businesses, quality cyclicals and selected financial companies. |
| Most important near-term risk | Oil-driven inflation that keeps bond yields elevated or prompts further Fed tightening. |
| Best evidence for a durable recovery | Better market breadth, resilient earnings revisions, healthier AI cash flow and a 10-year Treasury yield that stops climbing. |
| What could overturn this forecast? | Renewed supply disruptions, rising yields, widening credit spreads or weakening employment and profits. |
Forecast verdict: A rebound is plausible before early February, but the strongest investment opportunities may lie beneath the headline S&P 500 and Nasdaq figures. Broad-market index gains are not necessarily the same thing as a healthy market.
S&P 500 Prediction: Bull, Base and Bear Cases Through February 2027
We prefer scenarios over a precise point target. An index forecast of exactly 8,000 sounds authoritative, but little in the current political, energy or monetary environment justifies that precision.
| Scenario | Three-month return | S&P 500 February 3 range | Conditions |
|---|---|---|---|
| Bullish recovery | +6% to +12% | 8,023–8,477 | Energy moderates; yields stabilize; AI cash generation improves; breadth strengthens. |
| Base case: selective gains | −2% to +5% | 7,418–7,947 | Strong earnings, but restrictive rates and periodic political or AI volatility limit upside. |
| Bearish repricing | −15% to −8% | 6,434–6,963 | Oil surges, inflation accelerates, yields rise or investors reduce valuation multiples. |
These scenario ranges are calculated from the November 3 closing value—not surveyed Wall Street consensus targets, probabilities or statistical confidence intervals. The paths within each scenario will almost certainly be uneven. The ranges separate distinct scenarios; intermediate levels remain possible.
Why the outlook is more promising than the recent selloff suggests
The Nasdaq-100 had fallen more than 10% from its October 6 record by November 2. Yet the S&P 500 stood only about 3% below its October 6 record as of November 3, revealing considerable variation within the market.
At the same time, the broader economic picture is not one of collapsing corporate profits.
FactSet reported on October 30 that blended third-quarter S&P 500 earnings growth stood at 30.2% year over year, with 82% of reporting companies exceeding EPS estimates.
The catch: their aggregate earnings surprise was only 1.9%, well below the five-year average of 7.5%. FactSet also put the index’s forward 12-month price/earnings ratio at 18.7, below its five- and ten-year averages.
Investors POV: Profits are growing, but the market wants proof that future profits will arrive—and that expensive capital projects will earn attractive returns.
Three Market Experts, Three Different Paths to 2027
Wall Street’s leading forecasters disagree about timing and risk more than they disagree that American businesses still possess opportunities for growth.
Tom Lee, Fundstrat — bullish on an AI recovery.
In a November 2 research update, Lee argued that AI-related stocks could recover after the midterm election, citing the correction, credit-market behavior and political uncertainty. His argument is that a selloff driven by investor positioning can create opportunities even when underlying AI demand remains strong. That is a recovery thesis, not proof that a market bottom is already confirmed.
Michael Wilson, Morgan Stanley — correction may be nearing completion.
On November 2, Wilson’s team described the market decline as being in its “final innings.” They pointed to extensive damage already suffered by individual stocks and saw potential in quality cyclical businesses whose valuations had declined.
The caution: future policy surprises and weak free-cash-flow conversion could still damage returns.
Ed Yardeni, Yardeni Research — positive long-term outlook, greater near-term caution.
Yardeni lowered his year-end 2026 S&P 500 target to 7,900 and moved his 8,400 target to mid-2027. He identified renewed Middle East conflict and a potential oil-price surge as reasons for caution. Those are targets for different dates and should not be mistaken for February 2027 forecasts.
These positions can coexist. A market bottom may be developing, yet the recovery can remain turbulent, and investors who buy a business with poor financing economics can still lose money during an improving market.
The Five Forces That Will Determine Stock Prices Over the Next Three Months
The following is the practical version of the framework explored in our Stock Market Factors and Forecasts guide.
The five forces interact; watching any one of them in isolation is a frequent source of false confidence.
1. Inflation and the Federal Reserve: the danger of expecting easy money too soon
The Federal Reserve raised its policy-rate range in September and held it at 3.75%–4.00% on October 28. Two policymakers voted for a further increase at the October meeting.
That is a very different backdrop from a market confidently awaiting imminent cuts. If inflation cools, investors may reward growth companies even without an immediate cut. If wages, energy or service prices accelerate, the Fed may remain restrictive—or tighten again.
The December 8–9 meeting, which includes new economic projections, may be the most consequential scheduled policy event of this forecast window.
Investors Should Watch: CPI, core inflation, wage growth, Fed guidance and the expected path for short-term rates.
2. The 10-year Treasury yield: a valuation ceiling for expensive stocks
Long-term borrowing costs are not set solely by the Fed. The bond market also prices government deficits, inflation compensation, bond supply and the future cost of money. The 10-year Treasury yield has recently been near 4.9%, a level that forces investors to compare the relatively predictable return on high-quality bonds with the uncertain future profits of richly valued equities.
A sustained move materially above 5% would be an important warning, particularly if accompanied by rising credit spreads. onversely, stable or falling yields could help higher-quality technology and industrial-growth businesses recover without any dramatic change in earnings.
Investors Should Watch: the 10-year yield, high-yield corporate credit spreads, Treasury auctions and earnings estimates.
3. AI spending: real demand, but not every AI stock is a good investment
AI is still an extraordinary source of demand for chips, electrical equipment, power systems, data centers and cloud capacity. The important issue now goes from whether AI adoption is accelerating to who will capture the profits, how quickly, and at what financing cost (i.e. ai bottleneck stocks).
UBS recently noted strong demand growth in major cloud businesses while highlighting risks from overinvestment, financing, monetization and the possible displacement of existing revenue streams.
In other words, a strong AI sales report can still lead to a falling share price if cash generation is disappointing. That makes financially durable cloud platforms and suppliers of essential infrastructure more interesting than companies dependent on continual equity issuance, expensive debt or optimistic valuations.
Investors Should Watch: cloud revenue, hyperscaler capital expenditure, free cash flow, backlog quality, financing costs and the ratio of earnings growth to valuation.
4. Politics, oil and trade: the emotional catalyst that can change the forecast overnight
The November 3 midterm elections matter because congressional control influences legislative priorities, oversight, spending and the debt-ceiling negotiations ahead. It’s the struggle or standoff between the two that threatens to stall the economy.
The presidency also retains important influence over tariffs, diplomacy, regulation and military policy. But neither a Democratic nor Republican result guarantees higher or lower stock prices. The market’s reaction depends on what was already expected and on the actual policies that follow.
Oil is the immediate economic transmission mechanism. Geopolitical escalation can raise transport, food and industrial costs, erode purchasing power and complicate the Fed’s inflation fight. A durable de-escalation would work in the opposite direction.
The EIA’s October forecast expected Brent prices to moderate through 2027, but explicitly warned that Middle East disruptions could cause unusual volatility. Its forecast predates some recent events and should not be read as a live oil-price prediction.
Politics also works through psychology: investors may react and sell first then evaluate policy later. That is why risk control matters most when political certainty seems least attainable.
Investors Should Watch: Brent and WTI crude, the Strait of Hormuz, U.S.–Iran negotiations, tariff announcements, congressional budget negotiations and defensive market positioning.
5. Corporate earnings, consumer demand and market breadth
An S&P 500 rally driven by a few giant technology stocks can give investors a misleading sense of security. The healthier signal is participation: industrials, financials, healthcare, small caps and other economically sensitive industries advancing alongside technology.
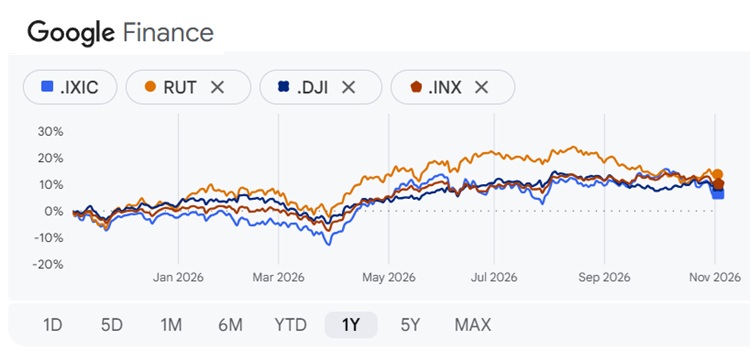
As of November 3, the Russell 2000 was up 13.3% in 2026, versus 10.6% for the S&P 500, 9.2% for the Nasdaq Composite and 7.7% for the Dow. Those figures show that gains have not been confined to the biggest technology businesses, but they do not guarantee a small-cap rally from here. The key is whether more companies begin beating revised earnings estimates while households maintain spending and employers sustain jobs.
More than one positive trading day is needed to confirm a durable change in market leadership.
Investors Should Watch: equal-weight versus capitalization-weighted S&P 500 returns, percentage of stocks above their 200-day averages, earnings revisions, retail spending and credit conditions.
S&P 500 Prediction for Next 3 Months
November, December and January: What Each Month May Offer Investors
November 2026: a test of political expectations and the market bottom
Election results may remove one uncertainty but reveal others.
The October employment report on November 6 and CPI on November 10 will test whether inflation is moving in a direction that markets can live with.
Expect fast rotations between AI, energy, defensives and cyclicals. A convincing recovery would include better market breadth and calmer Treasury yields, not merely another big Nasdaq day.
Investor approach: Build a focused watchlist; consider staggered entries rather than a single bet on an election rally.
December 2026: the Fed and the possibility of a year-end recovery
The November jobs report on December 4, the December 8–9 FOMC meeting, and the December 10 CPI report will shape expectations for the first quarter of 2027. A year-end recovery is possible if investors gain confidence that earnings can absorb high borrowing costs.
But traditional December seasonality is not a substitute for improving credit conditions or corporate fundamentals.
Investor approach: Compare actual earnings and cash flows with the assumptions behind each holding’s valuation. Watch industrial and quality-growth participation.
January 2027: the earnings reality check
The December jobs report arrives January 8, December CPI on January 13, and the next FOMC decision on January 27.
Later in January, quarterly company results and management commentary will become the more important test of 2027 profit expectations. Rising guidance across several sectors would strengthen the bull case; high AI spending combined with disappointing free cash flow would challenge it.
Investor approach: Review whether the recovery is broadening or becoming concentrated again. Rebalance positions that rely on a single optimistic assumption.
Which Stocks and Sectors Look Most Promising for the Next Three Months?
Rather than treating every beaten-down stock as a bargain, consider where business demand, pricing power, cash generation and reasonable valuation intersect.
| Opportunity | Illustrative watchlist | Why it deserves attention | What would make us cautious |
|---|---|---|---|
| Power and AI infrastructure | Eaton (ETN), Vertiv (VRT), GE Vernova (GEV) | Power, cooling and electrical bottlenecks could persist even if speculative AI valuations contract. | Excessive valuation, order cancellations, margin compression. |
| Profitable cloud and AI platforms | Microsoft (MSFT), Alphabet (GOOGL), Amazon (AMZN) | Large installed customer bases and cloud revenue offer potential AI monetization. | Spending outpaces incremental cash flow; expensive shares. |
| Quality industrial cyclicals | Caterpillar (CAT), industrial-sector ETF (XLI) | Could benefit if business investment and manufacturing activity stay resilient. | Slowing orders, tariff costs, rising financing rates. |
| Financial leaders | JPMorgan Chase (JPM), financial-sector ETF (XLF) | Can participate in economic resilience and improving credit demand. | Credit losses, funding pressures, curve volatility. |
| Diversified market participation | S&P 500 equal-weight ETF (RSP), small-cap ETF (IWM) | Offers exposure beyond the largest technology stocks if breadth improves. | Weak earnings outside mega-caps or tighter small-company credit. |
Energy and defense stocks may offer event-driven opportunities or portfolio diversification, but their upside is sensitive to developments that are difficult to forecast.
A falling oil price, for example, can help the broader economy while disappointing energy producers. For a wider selection and valuation discussion, see our Best Stocks to Invest In and Nasdaq Forecast reports.
Is Now a Good Time to Buy Stocks—or Should Investors Wait?
The decision is not simply “buy the dip” versus “stay in cash.”
Some well-capitalized companies may already offer attractive long-term entry points, while certain high-growth stocks can keep falling even after a large correction. What matters is the gap between price and realistic future cash generation. A practical three-part discipline is to (1) separate a strong business from an attractive share price, (2) stage purchases to preserve flexibility, and (3) monitor what would invalidate the thesis.
An investor who can hold through a multi-year recovery may act differently from someone who needs the money in February. The strongest reason to buy over the next three months would be a combination of earnings resilience, stable yields and improving participation. The strongest reason to remain cautious would be widening credit stress or an oil-and-inflation shock that damages both earnings and valuation multiples.
For developments between monthly updates, see our Stock Market Forecast for Next Week.
Frequently Asked Questions About the Next Three Months
Will the stock market go up in the next three months?
Our November 3 forecast leans toward modest gains by February 3, 2027, but expects a volatile path. The S&P 500 base-case range is 7,418–7,947, and an oil shock, renewed inflation or disappointing AI-related profits could produce further declines.
Could the U.S. stock market crash before February 2027?
Yes. A sharp decline remains possible, particularly if energy costs surge, Treasury yields rise substantially, credit spreads widen or major companies reduce earnings forecasts.
A crash is not the base case; a bearish three-month scenario would put the S&P 500 in a broad 6,434–6,963 range.
Will the Fed cut interest rates by January 2027?
Investors should not count on a near-term cut. The Fed raised rates in September and held them at 3.75%–4.00% in October.
The December 8–9, 2026 and January 26–27, 2027 meetings will reassess inflation, labor conditions and financial conditions. Rates could remain elevated or rise further.
How will the 2026 midterm elections affect the stock market?
The election can change congressional oversight, legislation, fiscal negotiations and expectations about regulations, but market reactions also depend on what was priced in beforehand. The president retains significant influence over tariffs and foreign policy. Earnings, oil prices, inflation and Treasury yields may ultimately matter more than the party winning a chamber of Congress.
What are the best stocks to watch over the next three months?
Promising research areas include financially resilient AI infrastructure, electrical equipment, established cloud companies, selected industrials and diversified exposure beyond mega-cap technology.
Whether any particular stock is a good buy depends on current valuation, balance-sheet strength and the investor’s horizon.
Final Outlook: Opportunity Is Returning, but Investors Must Be Selective
There is reason to believe the next three months could mark the transition from a painful technology-led correction toward a healthier 2027 investment environment.
The crucial question is whether earnings growth, cash generation and a broader group of companies can take over from enthusiasm about AI spending alone. For now, our forecast favors a selective rebound—not an unquestioning return to speculative buying.
Monitor oil, inflation and the 10-year Treasury yield. Watch which companies turn sales and backlogs into actual cash. Above all, look for a rally supported by more than a handful of giant stocks. The real opportunity may be through identifying the durable businesses the market is temporarily pricing as though the future has become much worse than it really is.
Review some selected stock market expert predictions, and the Dow Jones 2027 forecast for unique looks at the coming investment year.
This is market analysis and scenario research, not individualized financial advice. Market forecasts are inherently uncertain and the scenarios are not guarantees.